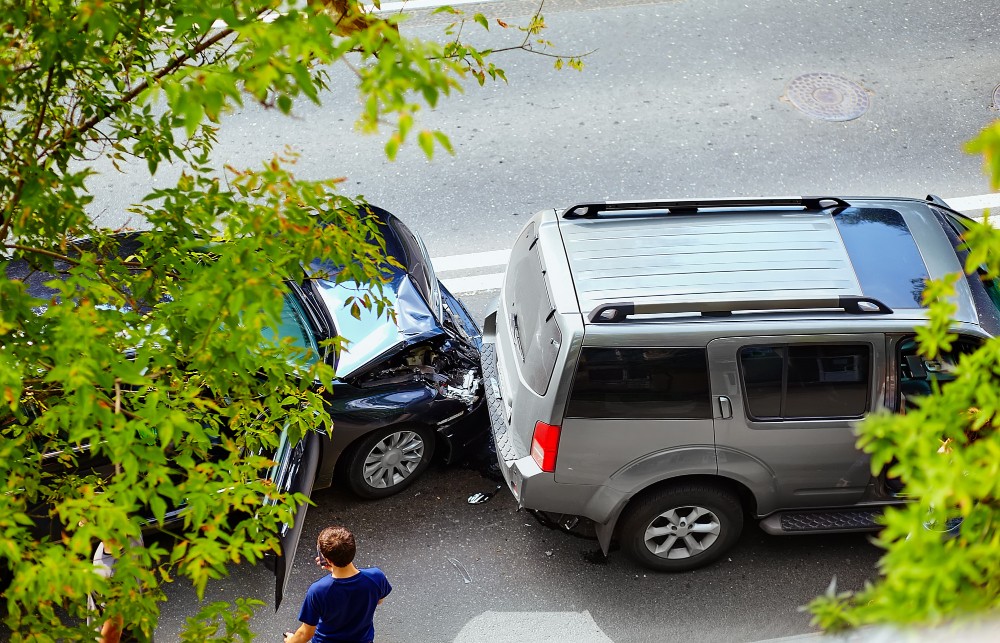
An accident brings enough to deal with: repairs, paperwork, maybe a rental car. Then the renewal notice arrives with a higher price. If you’re asking how much does insurance go up after an accident, the short answer is that it depends on who was at fault, how serious the accident was and how your insurer prices risk. This article explains what drives the increase, how long it lasts and what you can do to bring your rate back down.
In a nutshell: After an at-fault accident, insurance goes up at your next renewal and comes back down once the surcharge expires, typically after 3 to 5 years.
How much does insurance increase after an accident?
There’s no single number. How much does insurance increase after an accident depends on several factors working together:
- Fault. At-fault accidents lead to the largest increases.
- Severity. Claims with injuries or high repair costs usually raise rates more than minor damage.
- Your driving record. A first accident on a clean record is treated differently from a second or third incident.
- Your state. State rules affect how and when insurers can apply surcharges.
- Your insurer. Each insurer weighs accidents differently, so the same accident can lead to very different prices.
- Accident forgiveness. If your policy includes it, your first at-fault accident may not raise your rate at all.
The increase is added to a base rate that already reflects your age, vehicle, location and coverage. For a closer look at how that base is built, read what is the average cost of car insurance.
At-fault vs. not-at-fault accidents
At-fault accidents are the main cause of post-accident increases. If another driver was responsible, your rate often changes little or not at all, and some states limit surcharges for not-at-fault accidents.
Claims for events like hail, theft or hitting an animal fall under comprehensive coverage. These usually affect your rate less than an at-fault collision. To see how that coverage works, read what is comprehensive car insurance.
How much will my insurance go up with an at-fault accident?
If you’re asking how much will my insurance go up with an at-fault accident, the most useful answer is: it depends on the insurer as much as the accident. Insurers use their own rating formulas. One may add a steep surcharge for a first accident, while another weighs your years of clean driving more heavily.
That’s why your renewal price isn’t the only price available to you. Comparing quotes after an accident shows how differently insurers see the same record.
Wondering how other insurers would price your record? Compare auto insurance quotes
Should you file a claim for minor damage?
For very small damage, paying for repairs yourself can sometimes cost less than a surcharge over several years. Your policy may still require you to report the accident, so contact your insurer before deciding. If another person was injured or another vehicle was damaged, report it and let your insurer handle the claim.
When does car insurance go down after an accident?
Increases don’t last forever. Here’s how the timeline usually works:
- The increase starts at renewal. Insurers usually apply a surcharge when your policy renews, not in the middle of a term.
- The surcharge period runs for several years. Most insurers look back 3 to 5 years, depending on the insurer and your state.
- The accident ages off. Once the accident falls outside that look-back period, the surcharge is removed at your next renewal.
So, when does car insurance go down after accident surcharges drop off your record? Usually at the first renewal after the look-back period ends. The drop isn’t always automatic, though. Other factors may have changed, so review your renewal price when it arrives.
Your age also affects your rate over time, separate from any accident. Our guide on at what age does car insurance go down explains how that works.
When an accident leads to an SR-22
Some serious violations connected to an accident, such as driving without insurance or a DUI, can lead your state to require an SR-22. This filing proves you carry the required coverage, usually for several years. Our guide on what is an SR22 explains how the process works.
How to lower your rate after an accident
You can’t remove an accident from your record, but you can manage what you pay:
- Compare quotes at renewal. Insurers weigh accidents differently, so your current price may not be your lowest option.
- Take a defensive driving course. Some insurers and states offer a discount for completing an approved course.
- Review your deductible. A higher collision deductible lowers your premium but raises what you pay after a claim.
- Review coverage on an older car. Dropping collision on a low-value car can cut costs, but it shifts more risk to you. Read what is liability only insurance before you decide.
- Ask about accident forgiveness. It won’t erase a past accident, but it can protect your rate from a future one.
- Place your home and auto policies through one agency. Many home insurers offer a discount when your auto policy is also placed through Nsure, even with a different insurer.
Rates change for many reasons, not just accidents. Our guide on how often should you shop for home and auto insurance covers when a comparison makes sense.
Nice act. Now show me the coverage.
When insurers compete for your policy, price is the opening number, not the verdict. A lower quote after an accident only helps if it covers you the same way. Compare these points side by side:
- Liability limits, matched to your current policy.
- Collision and comprehensive deductibles.
- Accident forgiveness, and whether it’s included or an add-on.
- Discounts for safe driving, courses or multiple policies.
- Any coverage removed to reach a lower price.
Ready to see how your record is priced elsewhere? Get an auto insurance quote
Key takeaways
- The increase varies. Fault, severity, your record, your state and your insurer all affect how much your rate goes up.
- At-fault accidents matter most. Not-at-fault accidents and comprehensive claims usually have less effect.
- Increases start at renewal and typically last 3 to 5 years.
- Rates go down once the accident ages off, usually at the first renewal after the look-back period.
- Insurers price accidents differently. Comparing quotes is one of the most direct ways to lower your rate after an accident.
Compare auto insurance with Nsure
At Nsure, we make 100+ insurers compete for you. You answer once, and we share your details with insurers in our network rated A- or better. You then see real quotes side by side and choose on price and coverage. A quote can change after the insurer reviews your driving record. Using Nsure is free: the insurer you choose pays us a commission, and you’re never obliged to buy or switch. Want to talk it through? Our licensed agents are available at 561-288-9700, Monday to Friday, 9 AM to 5 PM ET.
Make 100+ insurers compete for you. Compare insurance prices. Understand the coverage.