Does homeowners insurance cover earthquake damage, or is a separate policy required?
Amelia Szulc
Share this article
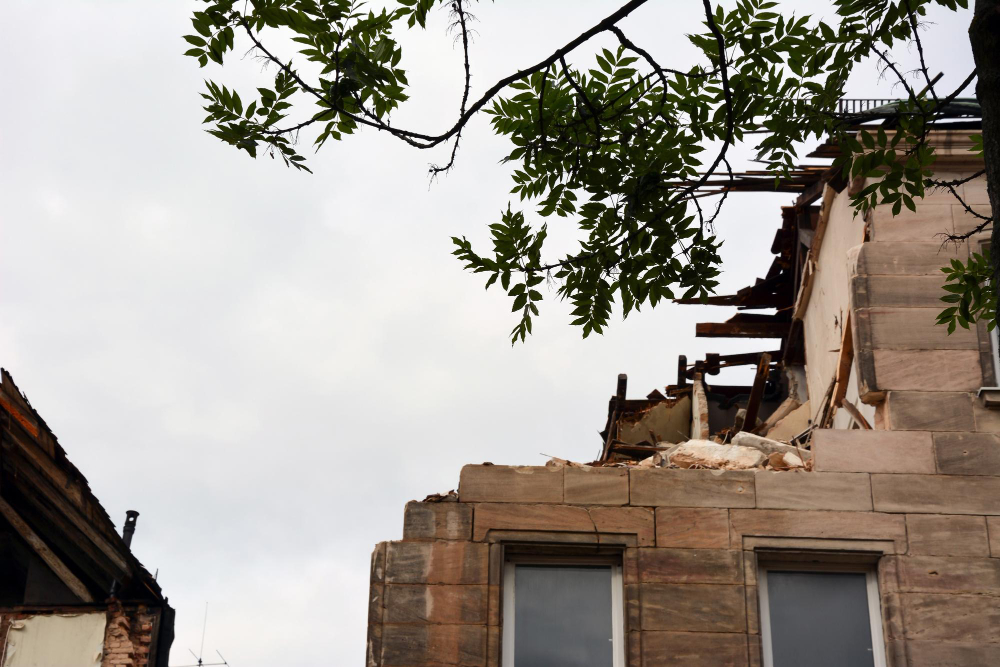
Earthquakes give no warning, and the damage can reach from a cracked chimney to a home that can’t be lived in. Many homeowners assume their policy already protects them. If you’re asking does homeowners insurance cover earthquake damage, the answer for a standard policy is no. This article explains what is excluded, what earthquake insurance covers, what drives its cost and how to decide whether you need it.
In a nutshell:No, standard homeowners insurance excludes earthquake damage, so you need a separate earthquake policy or an endorsement to cover it.
Does homeowners insurance cover earthquake damage?
No. Standard homeowners policies exclude earthquake damage. The exclusion usually sits under “earth movement,” which also covers landslides, mudflows and sinkholes in most policies.
There is one important exception. If an earthquake causes a fire, your homeowners policy typically covers the fire damage. The shaking itself stays excluded, but a fire that follows it is a covered peril.
Earth movement also explains why cracked or shifting foundations are often a coverage question. Our guide to does home insurance cover foundation repair covers when a foundation claim is approved and when it’s treated as maintenance.
What is earthquake insurance?
If you’re wondering what is earthquake insurance, it’s coverage built specifically for damage caused by the ground shaking. You can usually get it in one of 3 ways:
An endorsement added to your homeowners policy, where insurers offer it.
A standalone earthquake policy from a private insurer.
A state program, such as the California Earthquake Authority, sold through participating insurers in California.
Some homeowners also get earthquake protection through a difference in conditions policy, which fills gaps a primary property policy leaves open. Read what is DIC insurance to see how that works.
What does earthquake insurance cover?
What does earthquake insurance cover depends on the policy, but most include these parts:
Coverage part
What it pays for after an earthquake
Dwelling
Repairing or rebuilding the structure of your home
Personal property
Belongings damaged by the shaking, such as furniture and electronics
Loss of use
Extra living costs, such as a rental, while your home is unlivable
Building code upgrades
Some policies help pay to rebuild to current code
Earthquake policies often leave some things out or offer them only as options:
Detached structures such as fences, pools and driveways.
Exterior masonry veneer, such as brick or stone facing.
Landscaping.
Your car, which is covered under the comprehensive part of an auto policy.
There is no single price. So how much is earthquake insurance for your home? It depends on factors specific to your property:
Location. Distance from active faults and local soil conditions carry the most weight.
Construction. Wood-frame homes often flex better than brick or masonry homes.
Age and retrofitting. Older homes that have been bolted to their foundation may qualify for lower rates.
Coverage limits. Higher dwelling and personal property limits raise the premium.
Deductible. A higher deductible lowers the premium but raises what you pay after a loss.
Your earthquake insurance cost also depends on how the deductible works. Earthquake deductibles are usually a percentage of your dwelling coverage, not a flat dollar amount. The California Earthquake Authority, for example, offers deductibles from 5% to 25%. On a home insured for $400,000, a 15% deductible means you’d cover the first $60,000 of damage yourself.
That’s why the premium alone doesn’t tell the full story. Generic prices online are rarely accurate for a specific home, which we explain in how much should home insurance cost.
Do I need earthquake insurance?
Mortgage lenders rarely require it, so the decision is usually yours. If you’re asking do I need earthquake insurance, these questions help:
Do you live near an active fault? Risk is highest on the West Coast and in Alaska, but parts of the central and eastern US also face earthquake risk.
Could you afford to rebuild without it? Think about your savings, your mortgage balance and the cost of rebuilding at today’s prices.
Could you cover the deductible? A percentage deductible can mean a large out-of-pocket amount.
How is your home built? Older, unreinforced homes tend to suffer more damage.
Your dwelling limit is the base for both your homeowners and earthquake coverage. To understand that number, read what is dwelling coverage.
When insurers compete for your policy, price is the opening number, not the verdict. If you’re comparing earthquake options, put these points side by side:
Deductible percentage and the dollar amount it works out to
Dwelling limit and whether it matches your rebuild cost
Separate deductibles for dwelling and personal property, if any
Loss of use limit and how long it lasts
Building code upgrade coverage
Exclusions for masonry veneer, detached structures and landscaping
Key takeaways
Earthquakes are excluded. Standard homeowners policies don’t cover earthquake damage, including the most common HO-3 form.
Fire after an earthquake is covered under your homeowners policy.
Earthquake coverage is separate. You can add it as an endorsement, buy a standalone policy or use a state program where one exists.
Deductibles work differently. They’re usually a percentage of your dwelling coverage, so check the dollar amount.
The decision is personal. Weigh your location, your home’s construction and whether you could rebuild without coverage.
Compare home coverage with Nsure
At Nsure, we make 100+ insurers compete for you. You answer once, and we share your details with insurers in our network rated A- or better. You then see real quotes side by side and choose on price and coverage. A quote can change after the insurer reviews your details. Using Nsure is free: the insurer you choose pays us a commission, and you’re never obliged to buy or switch. If you have questions about earthquake coverage where you live, our licensed agents are available at 561-288-9700, Monday to Friday, 9 AM to 5 PM ET.
Make 100+ insurers compete for you. Compare insurance prices. Understand the coverage.
Amelia Szulc
About the author
Amelia is a UX writer whose job is to make sure no one has to read a sentence twice. With a background in literature and years of experience in editing and content design, she has spent a long time thinking about words — not the impressive ones, but the right ones. Her goal is to simplify complex topics and write in a language that resonates with people.